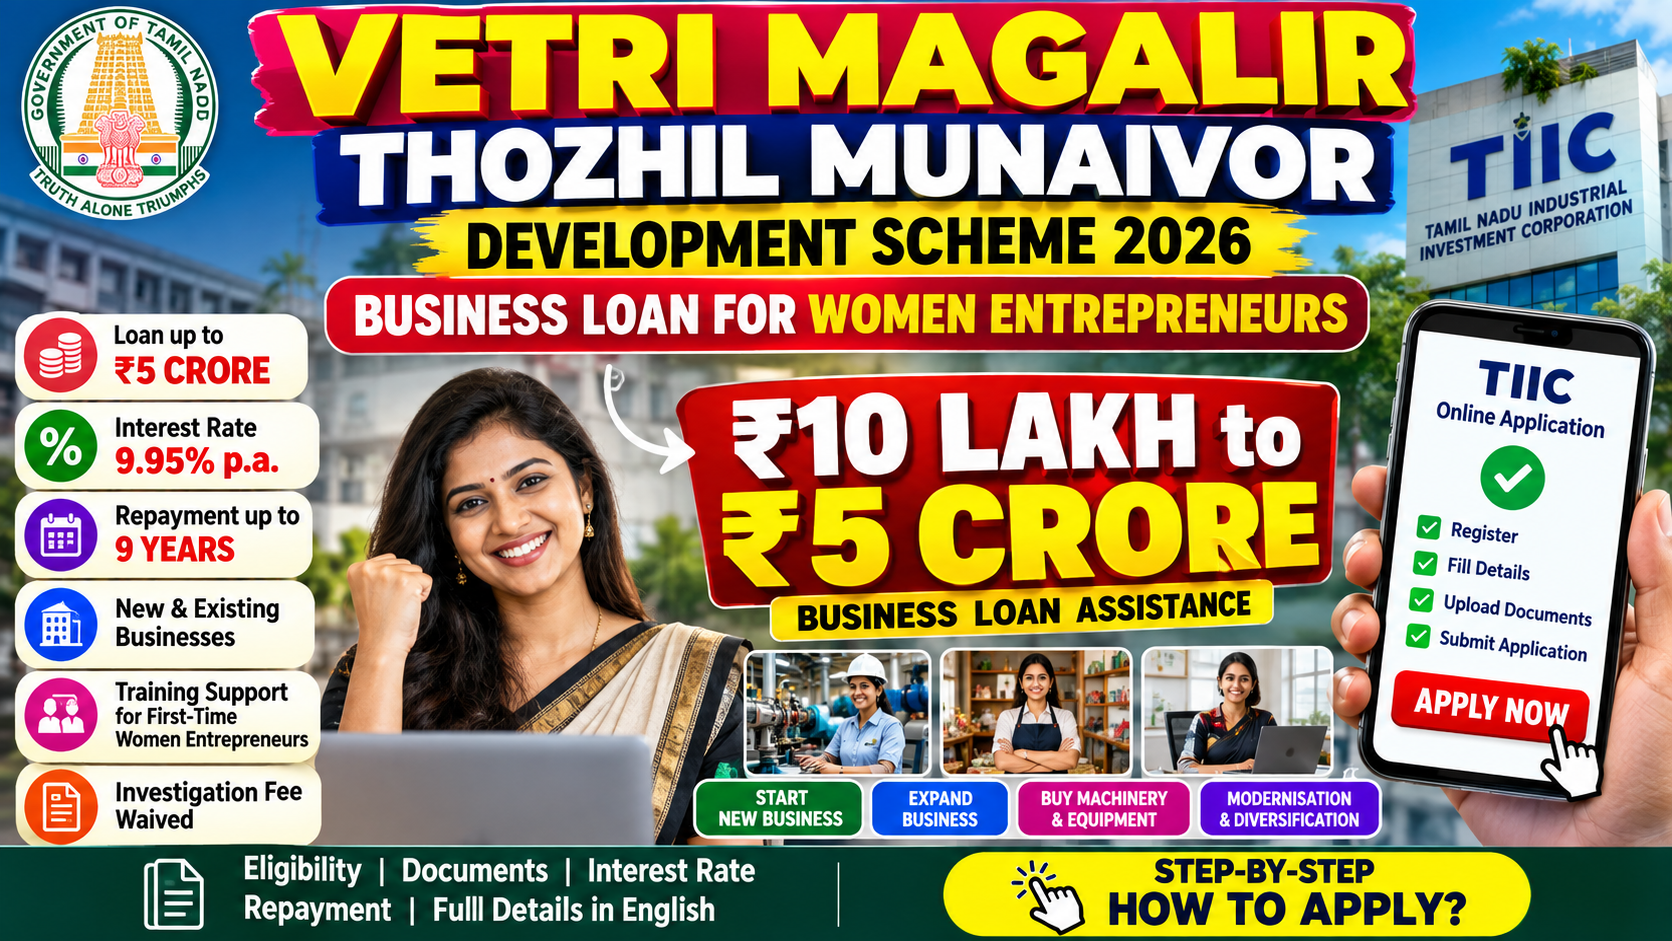
Starting a business requires more than just a good idea. For many women entrepreneurs, arranging the initial investment, purchasing machinery, setting up infrastructure and managing working capital can be a major challenge.
To support women who want to enter entrepreneurship or grow an existing business, the Tamil Nadu government has introduced the Vetri Magalir Thozhil Munaivor Development Scheme 2026.
The scheme is being implemented through the Tamil Nadu Industrial Investment Corporation (TIIC) and provides financial assistance to eligible women entrepreneurs for setting up new businesses and expanding, modernising or diversifying existing businesses.
One of the biggest highlights is the loan limit:
💰 Loan assistance from ₹10 Lakh up to ₹5 Crore
The scheme is therefore particularly relevant for women planning medium- and large-scale business projects.
But there are several important conditions that applicants should understand before applying.
This article explains the scheme, loan amount, contribution, interest rate, repayment period, collateral, CIBIL requirement, eligible businesses, documents and application process in simple English.
🔥 What Is the Vetri Magalir Scheme?
The Vetri Magalir Thozhil Munaivor Development Scheme is a women-focused business financing initiative designed to encourage more women to become entrepreneurs.
The scheme supports eligible businesses in the:
- Manufacturing sector
- Service sector
Financial assistance can be used for eligible activities connected with:
- Starting a new business
- Expanding an existing business
- Modernising a business
- Diversifying business activities
- Purchasing new machinery
- Purchasing equipment
- Purchasing land required for the project
- Constructing eligible business buildings
- Other approved project-related investments
The scheme is implemented through TIIC.
💸 How Much Loan Can You Get?
The loan limit under the scheme is:
Minimum: ₹10 Lakh
Maximum: ₹5 Crore
In other words, eligible applicants can seek financing starting from ₹10 lakh and going up to ₹5 crore.
However, the ₹5 crore figure is the maximum permissible limit, not a guaranteed amount for every applicant.
The actual sanctioned amount depends on the project and the applicant’s financial position.
📊 Loan Amount Examples
Here is a simple illustration of the possible project sizes:
| Business Project | Possible Loan Requirement |
|---|---|
| Small manufacturing unit | ₹10–20 lakh |
| Food processing unit | ₹20–50 lakh |
| Machinery-based business | ₹25 lakh–₹1 crore |
| Medium-scale manufacturing | ₹50 lakh–₹2 crore |
| Large expansion project | ₹1–₹5 crore |
The final amount will be decided after assessment of the project.
👩 Who Can Benefit From This Scheme?
The scheme is specifically aimed at women entrepreneurs.
One of the key conditions is that women entrepreneurs should hold at least 51% ownership/shareholding in the eligible business entity.
Eligible organisational structures include:
✔ Proprietorship / One Person Company
✔ Partnership Firm
✔ LLP
✔ Private Limited Company
✔ Public Limited Company
The ownership requirement must be satisfied according to the applicable scheme guidelines.
🏢 Can an Existing Business Apply?
Yes.
The scheme is not limited only to women starting a business for the first time.
Existing eligible businesses can seek assistance for:
- Expansion
- Modernisation
- Diversification
- Machinery purchase
- Equipment purchase
- Infrastructure development
This makes the scheme useful for both new entrepreneurs and existing women-led businesses.
💰 How Much Should You Contribute?
The applicant is also required to bring a portion of the project cost.
For New Businesses
The promoter contribution is:
20% of the project cost
For example:
₹10 lakh project → ₹2 lakh contribution
₹25 lakh project → ₹5 lakh contribution
₹50 lakh project → ₹10 lakh contribution
₹1 crore project → ₹20 lakh contribution
🏭 Contribution for Existing Businesses
For eligible existing businesses, the promoter contribution is:
15% of the project cost
For example:
₹20 lakh project → ₹3 lakh contribution
₹50 lakh project → ₹7.5 lakh contribution
₹1 crore project → ₹15 lakh contribution
These are examples based on the stated contribution percentages. The actual financing structure will depend on the project assessment and applicable TIIC rules.
📌 Important: 4:1 Debt-to-Equity Ratio
Another important point is the stated:
Debt-to-Equity Ratio: 4:1
This means the overall financing structure is assessed with the applicable debt and equity relationship, including existing liabilities where relevant.
Therefore, applicants should not simply calculate:
“I have 20% money, so I will automatically get 80% as a loan.”
The final loan structure will be determined by TIIC after evaluating the complete project proposal.
📉 What Is the Interest Rate?
The current stated prime lending rate for the scheme is:
9.95% per annum
The interest is calculated on a reducing balance basis according to the applicable loan terms.
This means the interest calculation is not simply a flat 9.95% on the original loan amount for the entire repayment period.
The actual EMI will depend on:
- Loan amount
- Interest rate
- Repayment period
- Moratorium
- Date of disbursement
- Other applicable loan terms
The current 9.95% rate was reduced from the earlier 10.20% rate as part of the scheme’s concessions.
⏰ How Long Do You Get to Repay the Loan?
The maximum repayment period is:
Up to 9 years
This includes a possible:
Moratorium period of up to 2 years
The exact repayment schedule will depend on the sanctioned loan and applicable conditions.
🧮 EMI Example – How Much Could You Pay?
To understand the approximate repayment burden, consider an example.
Suppose:
Loan = ₹10 lakh
Interest = 9.95%
Repayment = 7 years
The approximate EMI would be around:
₹16,600–₹16,700 per month
This is only an illustrative EMI calculation.
For a larger loan such as ₹50 lakh or ₹1 crore, the monthly repayment would be substantially higher.
Applicants should therefore calculate repayment capacity before selecting a large loan amount.
🏠 Is Property Security Required?
Yes, collateral/security requirements can apply.
According to the scheme guidelines:
New businesses / businesses operating for less than 3 years
Immovable property collateral equivalent to around:
40% of the loan amount
may be required.
Established businesses operating for more than 3 years
For businesses with a satisfactory operating record, the requirement may be around:
20% of the loan amount
The exact security requirement is subject to TIIC’s assessment and applicable rules.
📈 What CIBIL Score Is Required?
Credit history is another important eligibility factor.
The stated requirement includes:
Individual CIBIL Score: Above 600
For business entities, applicable credit/rating requirements may also apply.
Having a CIBIL score above the stated threshold does not automatically guarantee loan approval.
TIIC can also examine the business proposal, repayment capacity, existing liabilities and other financial information.
👩💼 First-Time Women Entrepreneurs Can Also Get Training
The scheme is not only about providing financial assistance.
First-time entrepreneurs can receive entrepreneurship-related training through the Entrepreneurship Development and Innovation Institute (EDII).
Training can help entrepreneurs understand:
- Business planning
- Financial management
- Marketing
- Business operations
- Entrepreneurship skills
- Business development
- Technology and innovation
This can be particularly useful for women entering business for the first time.
🏗️ What Can the Loan Be Used For?
Depending on project eligibility and approval, the loan can support expenses such as:
🏭 Machinery
Purchase of new machinery and production equipment.
🏢 Building
Eligible project-related building construction.
🌍 Land
Purchase of land required for the approved project.
⚙️ Equipment
Purchase of eligible business equipment.
📈 Expansion
Expansion of an existing business.
🔄 Modernisation
Upgrading an existing business with newer technology and machinery.
🔀 Diversification
Adding new products, services or business activities.
🧾 What Documents Should You Keep Ready?
Applicants should prepare the documents relevant to their business structure.
Commonly required documents may include:
- Aadhaar Card
- PAN Card
- Passport-size photograph
- Address proof
- Bank account details
- Bank statements
- Business registration documents
- UDYAM Registration, if applicable
- GST Registration, if applicable
- Project Report
- Machinery quotations
- Property documents, where applicable
- Partnership/LLP documents
- Company incorporation documents
- Income Tax Returns, where applicable
- Existing business financial statements
- Details of existing loans/liabilities
- Other documents requested by TIIC
The exact list can differ depending on the type and size of the project.
📑 Why Is a Project Report Important?
If you are applying for a business loan, your project report is one of the most important parts of the proposal.
Your report should clearly explain:
Business Idea
What product or service will you provide?
Investment
How much money is required?
Machinery
What machinery or equipment will you purchase?
Location
Where will the business operate?
Employment
How many people will be employed?
Revenue
How much turnover do you expect?
Profit
What is the expected profit?
Repayment
How will the business repay the loan?
A realistic and properly prepared project report can help the lender understand the business proposal.
📱 How to Apply for the Vetri Magalir Scheme?
Applicants should use the official TIIC channels.
Step 1 – Visit TIIC Official Website
Open your mobile browser and visit:
Make sure you are using the official tiic.org domain.
📱 Mobile Guide – Step 1
[ILLUSTRATIVE MOBILE SCREENSHOT]
Show a smartphone browser with:
Search:
TIIC Tamil Nadu
Then highlight:
Add a sticker:
“OFFICIAL WEBSITE”
Step 2 – Check the Online Loan/Application Facility
Once you open the official TIIC website, check the currently available online loan/application services.
The website and application process can be updated by TIIC, so always follow the latest instructions shown on the official portal.
📱 Mobile Guide – Step 2
[ILLUSTRATIVE MOBILE SCREENSHOT]
Show:
TIIC
Online Services
Loan / Application
with an arrow pointing towards the relevant option.
Add:
“START APPLICATION”
Step 3 – Register If Required
If the portal requires registration, enter your correct:
- Name
- Mobile number
- Applicant information
- Business details
The official TIIC customer registration page is:
Step 4 – Enter Your Business Details
Enter the information requested by the portal/application form.
This can include:
- Business type
- Business activity
- Project location
- Project cost
- Loan requirement
- Promoter contribution
- Existing business details
- Financial information
Check every field before proceeding.
Step 5 – Upload Documents
Upload the required documents in the requested format.
Make sure:
- Documents are readable
- Names match your application
- Files are not corrupted
- Scanned copies are clear
- Correct documents are uploaded
Do not upload unnecessary personal documents to unofficial websites.
Step 6 – Submit the Application
Review your application carefully before submission.
Check:
Applicant Name ✔
Mobile Number ✔
Project Cost ✔
Loan Amount ✔
Promoter Contribution ✔
Documents ✔
Then submit the application according to the portal instructions.
Step 7 – Save the Application Number
After submission, save your:
Application Number / Reference Number
Take a screenshot of the confirmation page.
You can also check the official TIIC application-status facility:
TIIC Application Status Tracking
📑 Where Can You Find Application Forms?
TIIC provides application forms through its official website.
You can check:
TIIC Application Forms – Official
Always download forms from the official TIIC website.
⚠️ Is There a Separate ₹5 Crore Online Portal?
Applicants should be careful about social-media posts that claim to provide an exclusive “₹5 Crore Vetri Magalir Application Portal.”
The safest approach is to begin from the official TIIC website and follow the application instructions currently provided there.
Do not enter Aadhaar, PAN, bank details or OTP information into an unknown website.
🚨 Beware of Fake Loan Agents
Because the maximum loan amount is ₹5 crore, scammers may use the scheme name to collect money from applicants.
Be careful if someone says:
❌ “Pay ₹1,000 and your loan will be approved.”
❌ “No documents required.”
❌ “₹5 crore guaranteed.”
❌ “CIBIL is not required.”
❌ “Send OTP to complete the government application.”
❌ “Pay commission before approval.”
Do not trust such claims without official verification.
💡 How Much Money Is Available Under the Scheme Overall?
The Tamil Nadu government has announced a ₹500 crore lending programme through TIIC under the Vetri Magalir initiative.
The programme is expected to benefit more than 500 women-led MSMEs and create thousands of employment opportunities.
This overall allocation should not be confused with the maximum ₹5 crore loan available to an individual eligible applicant.
⭐ Major Highlights at a Glance
| Feature | Details |
|---|---|
| Scheme | Vetri Magalir Thozhil Munaivor Development Scheme |
| Target | Women Entrepreneurs |
| Minimum Loan | ₹10 lakh |
| Maximum Loan | ₹5 crore |
| New Business Contribution | 20% |
| Existing Business Contribution | 15% |
| Debt-Equity Ratio | 4:1 |
| Interest Rate | 9.95% p.a. |
| Repayment | Up to 9 years |
| Moratorium | Up to 2 years |
| Individual CIBIL | Above 600 |
| Women Ownership | At least 51% |
| Main Sectors | Manufacturing & Services |
| Investigation Fee | No investigation fee |
| Implementing Agency | TIIC |
The above figures are based on the currently published scheme guidelines and may be updated by the authorities.
❓ Frequently Asked Questions
Can a woman who has never run a business apply?
Yes, eligible first-time women entrepreneurs can seek assistance. Entrepreneurship training is also part of the scheme support.
Is ₹5 crore free money?
No. It is a business loan and must be repaid according to the sanctioned terms.
What is the minimum loan?
The stated minimum loan amount is ₹10 lakh.
What is the maximum loan?
Eligible applicants can seek up to ₹5 crore, subject to project appraisal and approval.
What is the interest rate?
The currently stated rate is 9.95% per annum, subject to applicable lending terms.
How long can I take to repay?
The maximum repayment period is up to 9 years, including a possible moratorium of up to 2 years.
Can an existing business apply?
Yes. Eligible existing businesses can seek financing for expansion, modernisation and diversification.
Is collateral required?
Collateral requirements can apply. The stated level depends on whether the business is new/young or established.
Is CIBIL important?
Yes. The guidelines state that an individual’s CIBIL score should be above 600.
Can the loan be used to buy machinery?
Yes, eligible machinery and equipment purchases can form part of the approved project.
Where should I apply?
Start with the official TIIC website and follow the current application instructions.
📌 Final Takeaway
The Vetri Magalir Thozhil Munaivor Development Scheme 2026 is a significant business-financing opportunity for women entrepreneurs in Tamil Nadu.
The scheme provides for loans ranging from:
₹10 Lakh → ₹5 Crore
with a currently stated interest rate of:
9.95% per annum
and repayment of up to:
9 Years
Women can use the financing for eligible new businesses as well as expansion, modernisation and diversification of existing businesses.
However, applicants should understand that this is not a guaranteed ₹5 crore loan and not a free-money scheme.
The final loan amount depends on the business project, financial assessment, promoter contribution, credit profile, collateral requirements and TIIC approval.
If you are planning to apply, the best approach is to first prepare a strong project report, calculate how much you can realistically repay, arrange your promoter contribution and then approach TIIC through its official channels.
Official TIIC Links
Disclaimer
This article is intended for informational and educational purposes only. Scheme conditions, interest rates, eligibility criteria, documentation requirements and application procedures may change. Loan approval is not guaranteed and is subject to TIIC’s appraisal and applicable government/TIIC rules. Applicants should verify the latest information directly with TIIC before submitting an application or making any financial commitment.